How Felons Can Get Life Insurance and Finally Protect Their Family
Your criminal record doesn't disqualify you from life insurance. What matters is timing, offense type, and knowing which carriers actually say yes to felons.
You're at the right website. We've helped many felons obtain life insurance. A felony conviction doesn't erase your ability to get life insurance and protect your loved ones and family, but it definitely changes how you apply.
Most people with criminal records assume they're automatically disqualified from life insurance coverage. That's not true. Insurance companies care more about risk than your past. If you understand what they're actually evaluating, you can navigate the application process without wasting time or money on carriers that will reject you.
Life insurance for felons exists, but it's not a one-size-fits-all answer. Some carriers specialize in higher-risk applicants, while others won't touch anyone with a felony on their record.
Here's what you actually need to know to secure coverage that protects your family without overpaying or getting denied.
The Four Important Factors Life Insurance Companies Look At For People With a Criminal Record
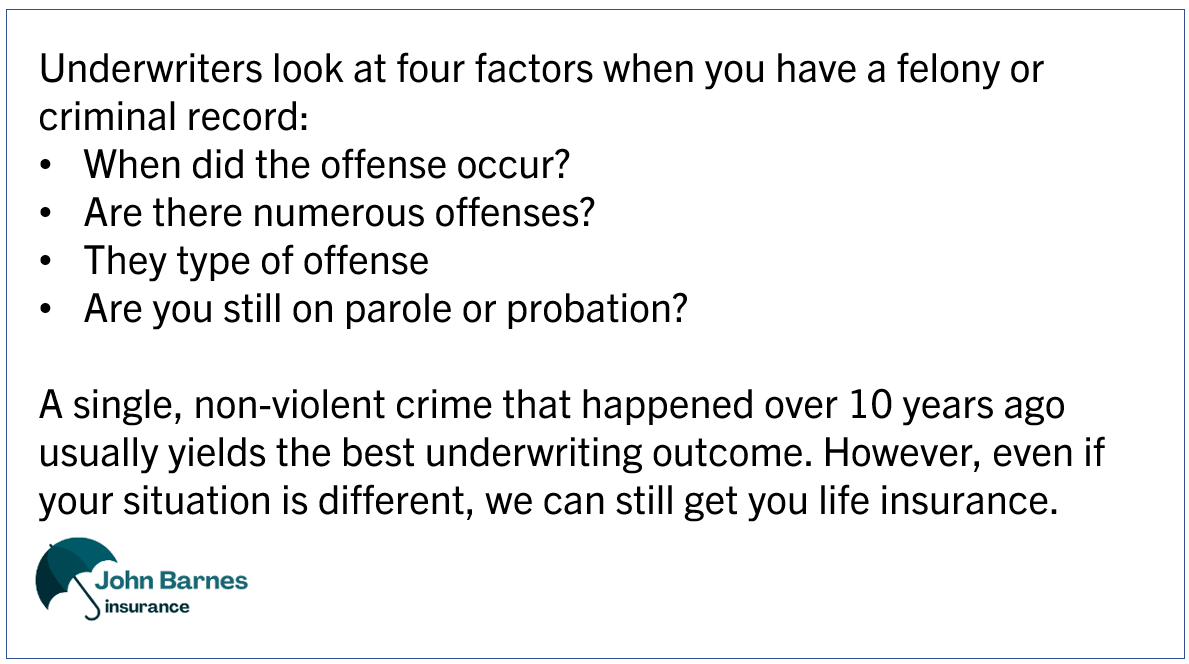
Before anything else, life insurance carriers and underwriters consider four key factors when evaluating a life insurance application from someone who is a felon or has a criminal record. These four factors include:
- When did the offense occur?
- Are there numerous offenses?
- The type of offense(s)
- Are you still on probation or parole?
Let's review these in more detail. Your answers help determine life insurance eligibility.
When Did the Offense Occur?
An offense from 10 years ago won't have the same underwriting impact as an offense from 1 or 2 years ago, all things being equal. For example, a life insurance application with a single, non-violent event from 10 years ago has a much better chance of approval (and a better rate) than the same event from 2 years ago.
The more time that's passed since your conviction, the better your chances for approval. Most carriers want to see at least five to seven years of clean living after parole or probation before they'll consider approving you for a standard policy. Some will work with you after two to three years if the offense was minor.
Are There Numerous Offenses or Felonies?
A single offense has less of an impact on underwriting than multiple offenses. Multiple offenses indicate a high risk. If you've read my articles on life insurance, then you know underwriters hate risk. In life insurance, they measure the risk of an unexpected or early death. Numerous criminal offenses indicate a higher-than-average risk. If your record shows escalating offenses, expect higher premiums or denials.
The Type of Criminal Offense
The type of felony or criminal offense definitely matters to underwriters. A non-violent, "white-collar" crime may have less underwriting impact than a violent crime. For example, non-violent crimes like fraud, embezzlement, or drug possession are viewed more favorably than violent crimes like assault, homicide, or sexual offenses. Financial crimes raise concerns about honesty, but they don't suggest physical danger to yourself or others. Misdemeanors also usually command a better rate than felonies.
Are You Still on Parole or Probation?
Carriers decline life insurance applications for those currently on parole or probation. The reason is that the person is still completing the terms of his or her sentence. Once you complete your sentence, your approval odds improve significantly. Some insurers will even offer standard rates if you've lived a stable lifestyle for a decade or more.
If you are on parole or probation, don't worry. I still have viable guaranteed issue life insurance options available. We have helped many people on parole, probation, or with serious crimes with this type of life insurance.
Wrap All of This Together
So, what does all this mean? It generally means a single, non-violent felony/offense from 10 years ago has a much better chance of approval than a felony from last year. Additionally, a single felony has a better chance of approval than multiple felonies or offenses. Finally, it doesn't matter if a person committed a white-collar crime 5 years ago. If he or she is still on parole or probation, all carriers decline the application (except for a few that we discuss later in the article).
The underwriting process isn't designed to punish you. It's designed to measure risk. If you can demonstrate that your conviction was an isolated incident and that you've lived responsibly since then, you'll have far better options than someone with recent or repeated offenses. Let's dig into underwriting, since it is the basis for approval or decline.
Life Insurance Underwriting Process for Felons
Life insurance companies have an extensive underwriting process for felons and people with criminal records. Traditional life insurance applications ask about your criminal history, and a felony triggers additional review. Insurers want to know what the conviction was for, when it happened, whether you served time, if you're still on probation or parole, and whether there's a pattern of criminal behavior.
Additionally, not all felonies are treated equally. As I mentioned, a single non-violent crime from 10 years ago is viewed very differently than multiple convictions or recent violent crimes. Drug-related felonies, DUIs elevated to felonies, fraud, theft, and white-collar crimes each come with their own underwriting concerns. Violent felonies like assault, homicide, or sexual offenses carry the most scrutiny and often result in declined applications or heavily rated policies.
The first section above provides an overview of what underwriters consider when you disclose a criminal record on your life insurance application. However, underwriters will want to go deeper. This is because of the risk you represent as a potential policyholder. They're assessing whether your past behavior suggests a higher likelihood of early death, which affects their payout risk. If your felony involved substance abuse, they'll worry about ongoing addiction. If it involved violence, they'll worry about future incidents. If it was financial fraud, they might question whether you'd commit insurance fraud.
Here are additional questions underwriters will want answers to.
Additional Life Insurance Questions For Felons and People with Criminal Records
Underwriters can access public records and run detailed background checks. Still, you should be honest and transparent on your application. They will want to know the answers to the following:
- Date of the incident
- What type of crime (misdemeanor or felony)?
- What type of class? (Class A, B, C, or D)
- Date of conviction and outcome of conviction
- Was there jail time?
- If so, how long?
- When were you released?
- Were you on parole or probation?
- Date of completion of parole or probation?
- Have you been fully discharged from all court proceedings?
- Are you currently working in gainful employment?
- If so, what is your occupation?
- Do you have a history of alcohol and drug use/abuse?
- Do you have a serious motor vehicle or reckless driving violations?
- Do you have any other diagnosed health conditions, including any corresponding prescription medication?
Of course, underwriters
will still review your health history, other lifestyle factors, etc., to build a complete underwriting profile.
Why Some Traditional Life Insurance Carriers Often Decline Felons
Most major life insurance companies use actuarial data showing that certain criminal histories correlate with higher mortality risk. The data supports this. So, if you've been incarcerated, you may have experienced health issues related to confinement. If your felony involved drugs or alcohol, there's a statistical likelihood of relapse. If it was violent, there's a risk of future violence. They have strict underwriting guidelines that automatically flag felony convictions. Many of these carriers, particularly those who offer instant-decision underwriting, automatically decline felons and people with criminal records.
These carriers aren't trying to be exclusionary. It's simply the documented connection between criminal history and mortality risk.
Here's where people with criminal records get stuck:
- They apply to the wrong company. Not all insurers have the same guidelines. Some are far more lenient than others, especially if your conviction is old and you've demonstrated stability since then.
- They apply too soon. If you're still on probation or parole, most carriers will automatically decline you. Waiting until you've completed your sentence dramatically improves your approval odds.
- They lie or omit details on the application. Insurance companies run detailed background checks. It'll be hard to fool an underwriter nowadays. However, if you're dishonest about your conviction and they find out, they can void your policy even after you've been paying premiums for years.
Traditional carriers also tend to offer fully underwritten policies, which require medical exams, background checks, and detailed questioning. These policies offer the best life insurance rates if you qualify, but they're also the most likely to decline applicants with criminal records.
That's why felons often need to explore all coverage options, including those that don't rely on perfect underwriting.
The Types of Life Insurance Felons Can Actually Get
Felons have three main life insurance options. Each has trade-offs in approval ease, cost, and coverage amount.
Fully underwritten policies with felon-friendly carriers. Some traditional life insurers specialize in higher-risk applicants and will approve people with felony convictions if enough time has passed and you meet other criteria. These policies require a medical exam and full disclosure of your criminal history, but if you qualify, you'll get better rates than simplified or guaranteed issue. The key is working with an independent agent (like me ) who knows which carriers are lenient and which ones automatically decline felons. Carriers accept these applications on a case-by-case basis, so if you work with me, I prequalify you with underwriters before you submit an official application. This way, we know what to expect from the underwriting process. You can get term life insurance or permanent life insurance, including whole life policies.
Simplified issue life insurance skips the medical exam and asks fewer health and lifestyle questions. Some carriers that offer simplified issue policies are more lenient with criminal records, especially if the conviction is older or non-violent. You'll still answer questions about your criminal history, but the approval process is faster and less invasive. The downside is that premiums are higher than fully underwritten policies, and coverage limits are usually capped at $250,000. We have helped many felons obtain life insurance through simplified issue life plans.
Guaranteed issue life insurance is the easiest to qualify for because there are no health questions and no background checks. Most agents will direct you to traditional guaranteed issue options capped at a $25,000 death benefit. Not us. We offer many guaranteed issue life insurance options, including some over $100,000. The one caveat is that you must work 20+ hours per week in gainful employment. If you are currently on parole or probation, these options provide a nice "bridge" until you qualify for more coverage or something better.
Each option serves a different purpose depending on your situation, and sometimes the best strategy is starting with guaranteed issue coverage. At the same time, you work toward qualifying for a better policy later.
Cost of Life Insurance for Felons
Felons will likely pay more for life insurance than someone without a criminal history. As I mentioned, it all comes down to risk. Underwriters have actuarial data that links criminal history to mortality risk. They adjust premiums accordingly.
For fully underwritten life insurance such as term life, underwriters adjust premiums through table ratings or flat extra fees. These increases raise your policy cost. However, focus on coverage, not necessarily cost. A table rating or a flat extra on a policy shouldn't be a deal breaker. Remember: your policy connects your loved ones to "peace-of-mind" in case of your unexpected death. As an independent agent, I can find you the lowest-cost life insurance for your situation.
Feel free to use the quoter below if you would like an estimate of what a policy could cost. Note: If you had a single, non-violent crime over 10 years ago, your health status might be standard or better, assuming you are in good health. Otherwise, expect a table rating or flat extra as I discussed.
Simplified issue and guaranteed issue life insurance options usually contain fixed prices. You have heard of the saying, "what you see is what you get." That applies to simplified issue and guaranteed issue. These plans cost more because carriers simplify underwriting or remove it completely. Additionally, they factor increased risk into their premiums.
You can check out and apply directly to our guaranteed issue life options here. Note: availability is based on age, state residency, and subject to change without notice.
What Most People With Criminal Records Get Wrong When Applying for Life Insurance
Don't apply directly to a single carrier. If you go to one insurance company and get declined, that declination gets reported to the Medical Information Bureau (MIB), and other carriers will see it. Too many declinations make you look like a high-risk applicant, even if the first company was just being overly cautious. Instead, work with an independent insurance agent who can shop multiple carriers on your behalf without triggering formal applications until you know which one is most likely to approve you.
Don't lie or leave out details. Insurance companies will find your criminal record. If you try to hide it, they'll discover it during the background check, and they'll deny your application. Worse, if you're approved and they find out later, they can void your policy and refuse to pay your beneficiaries. Full honesty upfront is always the best strategy.
Don't assume you're stuck with guaranteed issue forever. If you start with a guaranteed issue policy because it's your only option, you can always reapply for better coverage later. As more time passes since your conviction and you build a record of stability, your approval odds improve.
The biggest mistake felons make is assuming they have to settle for the worst life insurance policy available.
You don't. But you do need to approach the application process strategically.
The system isn't designed to keep you locked out forever. It's designed to reward people who demonstrate that they've moved past their criminal history.
When Should Felons Apply for Life Insurance and What to Expect
The best time to buy life insurance is always "now". However, in your case, timing is everything.
If your conviction happened recently, you're better off waiting a few years before applying for fully underwritten coverage. In the meantime, guaranteed issue or simplified issue policies can provide basic protection while you build your case for better rates later.
If your conviction is five or more years old, you're in a stronger position, as long as you're not on parole or probation. Many carriers will approve you, especially if the offense was non-violent and you've had no additional legal issues since then. You'll likely pay higher premiums than someone with a clean record, but you won't be stuck with the worst rates either.
If your conviction is 10 or more years old and you've lived a stable life since then, you may qualify for standard rates, depending on the carrier. Some insurers won't even ask about convictions older than a certain number of years, especially if they weren't violent.
Here's what to expect during the process: You'll fill out a detailed application that asks about your criminal history. Be prepared to provide court documents, proof of sentence completion, and any rehabilitation or restitution records. The insurer may request a background check and credit report. If you're applying for a fully underwritten policy, the carrier may request a medical exam.
Approval can take anywhere from a few days for simplified or guaranteed issue policies to several weeks for fully underwritten policies. If you're declined, ask why and use that information to apply to a different carrier with more lenient guidelines or work toward approval at a better time.
The key is persistence and working with an agent or broker who understands how different carriers handle felony convictions.
Frequently Asked Questions About Life Insurance and Felons
We answer frequently asked questions about life insurance for felons that we didn't answer already. If you have additional questions, contact us so we can help you find the right life insurance policy for your situation.
Is Group Life Insurance an Option for Felons?
Yes, group life insurance is certainly an option for felons. Most of the time, employers offer life insurance on a guaranteed issue basis. That means the carrier doesn't review felony records or anything like that. However, employers limit life insurance in a couple of ways:
* limited death benefit, like 1X or 2X salary
* usually not portable if you leave the employer
As mentioned, we can help you obtain the life insurance you need. Contact us.
Can Someone in Jail Obtain Life Insurance?
Likely, no. Even though many guaranteed issue life insurance options exist, which can be purchased up to $25,000 with no underwriting or work requirement, carriers do need the insured to be part of the application process. That could be hard if the applicant is in jail.
Can a Felon Get No-Exam Life Insurance?
It depends. If the offense was a single, non-violent offense that occurred over 10 years ago, then yes, a no-exam and instant-decision life insurance option is available. In any other scenario, a no-exam option is unlikely.
Can I get life insurance if I'm currently on probation?
Yes. Guaranteed issue life insurance options with death benefits of $100,000 or more exist. These are perfect for people on parole or probation who need some coverage now until they qualify for more or better coverage.
Don't listen to the other agents, brokers, and websites that tell you no. Life insurance for people on parole or probation is possible.
Do insurance companies check my criminal record even if I don't disclose it?
Yes. Insurance companies routinely run background checks through databases like the Medical Information Bureau (MIB) and other criminal record repositories. Failing to disclose a felony conviction can result in immediate denial and may be flagged across multiple carriers. Even if you're initially approved, the insurer can void your policy retroactively if they discover undisclosed criminal history, leaving your beneficiaries without coverage.
How much more expensive is life insurance for someone with a felony conviction?
Premium increases vary widely based on offense type, time since conviction, and policy type. If you had a single non-violent offense over 10 years ago and have maintained a stable lifestyle since, expect standard rates or better, as long as you're in good health. Otherwise, expect a table rating or a flat extra fee.
Will my life insurance beneficiaries be denied a payout because of my criminal record?
As long as you disclosed your criminal history accurately on your application and were approved, your beneficiaries will receive the death benefit regardless of your past conviction. The key is full transparency during the application process.
Are there any felony convictions that make me permanently uninsurable?
Very few convictions result in permanent uninsurability. Multiple violent felonies, recent convictions for murder or manslaughter, or patterns of escalating criminal behavior present the greatest challenges. However, even in these cases, guaranteed issue policies remain available. Some specialty insurers will work with applicants after 15 to 20 years of demonstrated stability, regardless of offense severity.
Can I get life insurance if my spouse has a felony conviction but I don't?
Yes. Your spouse's criminal record does not affect your individual life insurance application or rates. Each applicant is underwritten separately. However, if you're applying for a joint or second-to-die policy that covers both of you, the spouse with the felony conviction will impact the overall underwriting decision and pricing.
Do white-collar crimes like fraud or embezzlement affect life insurance differently than violent crimes?
Yes. White-collar crimes are generally viewed more favorably during underwriting because they don't suggest the same mortality risk as violent offenses. However, they raise concerns about honesty and the potential for insurance fraud. Violent felonies trigger concerns about personal safety and lifestyle risk. Both types require full disclosure, but violent convictions typically result in higher premiums or longer waiting periods before approval.
How long after completing my sentence should I wait before applying for life insurance?
For the best approval odds and competitive rates, wait at least 2 to 3 years after completing probation or parole for non-violent offenses, or 5 to 7 years for violent offenses. If you need coverage immediately after release, start with a guaranteed issue policy with a high death benefit, then reapply for better coverage once enough time has passed.
Will applying for life insurance and getting denied hurt my chances with other companies?
Yes. Multiple denials in a short time period can hurt your chances. Carriers report these denials to the Medical Information Bureau (MIB), which other insurers access during underwriting. Multiple denials can create a perception of high risk even if the first carrier was simply being conservative. This is why working with an independent agent who can informally shop your case before submitting formal applications is crucial.
Final Thoughts About Life Insurance for Felons
Life insurance isn't out of reach just because you have a felony. The options exist, and the right strategy can get you approved at a price you can afford. You can obtain life insurance to protect your loved ones and family.
The difference between getting declined and getting covered often comes down to timing, honesty, and knowing which carriers will work with your specific situation. If you approach the process with the right information, you'll find coverage that protects your family without forcing you to settle for overpriced or inadequate policies.
Do you have any questions or would like to know what options exist for you? Contact us or use the link below.
We only work in your best interest, not ours or a life insurance carrier's. We will find you the best option for your current situation. There is no risk to contacting us. If we can't help you, we will part as friends, and you can always reach back out to us if your needs change.